CPA Construction Trade Survey – further weakness to end 2023

CPA Construction Trade Survey – further weakness to end 2023

It was a weak end to 2023 and a subdued start to 2024 for firms operating throughout the construction supply chain, according to the CPA Q4 2023 Trade Survey.

Trade surveys for the fourth quarter of 2023 indicated that it was the worst quarterly performance since the first half of 2020, when activity was disrupted by lockdowns at the height of the pandemic, with declines in workloads for chartered surveyors and SME building contractors, and falls in sales for both heavy and light side product manufacturers.

There are still some areas of growth, however, and workloads growth reported by civil engineering contractors confirms that infrastructure continued to provide activity, a pocket of growth also identified by chartered surveyors, alongside public non-housing. Outside of these sectors, however, the constituent surveys point to little near-term pickup in the first half of 2024.

Falls in new enquiries were reported across SME contractors’ main sectors of focus of house building, commercial/industrial and RM&I, which mirrors the official ONS data on construction output, which has shown a notable decline since the second half of last year, and new orders, which have declined since the end of 2022. For product manufacturers, sales are expected to fall in 2024, whilst for chartered surveyors expectations of growing workloads were again restricted to infrastructure and public non-housing.

A stark downshift in the housing market, reluctance among homeowners to commit to large improvements spending and lower volumes of large commercial and industrial projects in the pipeline mean that demand is increasingly being flagged as a primary constraint or concern for activity over the coming 12 months, particularly when this combines with flatlining economic growth, a step-change to higher interest rates and financing costs, and continued uncertainty over input inflation as the Red Sea transport diversions continue.
Interaction between CIS and IR35

Interaction between CIS and IR35

If you’re a main contractor who is employing a sub-contractor through an intermediary, such as their own limited company, familiarity with the interaction between off-payroll rules (IR35), and the Construction Industry Scheme (CIS), is crucial, and so is an understanding of when the VAT reverse charge applies. This information sheet has been prepared by the JCT to help FIS members understand the interaction between CIS and IR35.
CPA Construction Trade Survey – further weakness to end 2023

Falling demand hits construction product manufacturers’ sales

The Construction Products Association’s latest State of Trade Survey for 2023 Q4 showed that manufacturers ended last year with a further fall in construction product sales on both the heavy side and light side – the sixth consecutive quarter of decline for heavy side manufacturers and the second fall for those on the light side. Manufacturers anticipate sales will decline over the next 12 months, citing a clear concern over the weak demand expected in 2024.

In 2023 Q4, a balance of 63% of heavy side manufacturers reported that sales of construction products decreased, marking the sixth consecutive quarter of decline and the weakest performance since 2020 Q2, at the height of the pandemic. Alongside this, 40% of light side manufacturers also reported a fall in product sales. This was the second quarterly decline but, equally, the lowest balance recorded since activity was paused during the early pandemic restrictions.

Looking to the next 12 months, demand was cited by 71% of heavy side manufacturers and 80% of light side manufacturers as the factor most likely to constrain growth during 2024. Consequently, 11% of heavy side manufacturers and 15% of light side manufacturers anticipated a fall in sales over this year.

The backdrop for costs was shown to be more favourable, however, with manufacturers reporting a continued easing in cost inflation. Price pressures were lower for raw materials, fuel and energy, which had all been major contributors to inflation over the last couple of years. Nevertheless, manufacturers reported continued upward pressure from wages & salaries.

Rebecca Larkin, CPA Head of Construction Research said: “Manufacturers had a challenging end to 2023 and there appears little to rally expectations for growth this year. Falls in new construction orders since the end of 2022 have now begun to filter through into lower construction activity, particularly in housing, commercial offices and warehouses and factories in the industrial sector. With flatlining GDP growth, a step-change in interest rates and build costs, and emerging risks around delays and cost rises related to the Red Sea shipping disruptions, it should come as no surprise that demand was flagged as the key concern for construction product manufacturing activity in 2024.”

Key survey findings include:

  • A balance of 63% of heavy side firms and 40% of light side firms reported that construction products sales fell in 2023 Q4 compared with Q3
  • This was the sixth straight quarter of decline for the heavy side and second for the light side
  • 11% of heavy side manufacturers and 15% of light side manufacturers anticipated a fall in sales over the next 12 months
  • 71% heavy side manufacturers and 80% of light side manufacturers cited ‘demand’ as the key concern for sales over the next 12 months
  • Cost balances continued to moderate but wages & salaries were the strongest cost pressures for both heavy side and light side manufacturers
CPA State of Trade Survey Q4 2023: declining demand impacts sales of construction product manufacturers

CPA State of Trade Survey Q4 2023: declining demand impacts sales of construction product manufacturers

The recent publication of the CPA’s State of Trade Survey Q4 2023 revealed a continued decrease in construction product sales for manufacturers in the previous year. This marks the sixth consecutive quarter of decline for heavy side manufacturers and the second decrease for those on the light side. Looking ahead, manufacturers predict a further decline in sales over the next 12 months, expressing worries about the anticipated weak demand in 2024.

CPI Inflation and Core CPI Inflation for January 2023 have shown moderate increases

CPI Inflation and Core CPI Inflation for January 2023 have shown moderate increases

The CPA’s weekly Economic and Construction Update provides an insightful summary of the latest economic and construction trends in the UK.


The CPA’s weekly Economic and Construction Update offers a comprehensive overview of the current economic and construction trends in the UK, including key indicators like CPI inflation, core CPI inflation, UK construction average weekly earnings, UK construction insolvencies, UK house price index, and the UK residential market survey. This resource is valuable for individuals keen on the UK construction sector, with a user-friendly contents page for easy navigation to specific sections of interest.


In the latest report, it is evident that CPI Inflation and Core CPI Inflation for January 2023 have shown moderate increases, reflecting the current economic climate. The ONS Construction Output data for December 2023 indicates steady growth in the sector, with promising signs for future developments. Additionally, the ONS Construction New Orders for Q4 of 2023 demonstrate a positive outlook for upcoming projects within the construction industry.

Moreover, the ONS UK Construction Employment figures for the same period reveal stable employment rates, highlighting the industry’s resilience and ability to provide job opportunities. On another note, the Insolvency Service UK Construction Insolvencies data for December 2023 shows a decrease in insolvencies, indicating a more robust financial landscape for construction companies.


Lastly, the ONS UK House Price Index for December 2023 presents an overview of the housing market, showcasing trends and fluctuations in property prices. Overall, the comprehensive update provides valuable insights into various aspects of the construction and housing sectors, offering a glimpse into the current state of the UK economy.

FIS Wage Rate Survey points to ongoing inflation and contractual pressures

FIS Wage Rate Survey points to ongoing inflation and contractual pressures

The FIS Wage Rate Survey H2 2023 conducted in January 2024 revealed that, across the trades, FIS members have continued to experience wage rate increases averaging around 4% in key trade occupations (the full index is available to contributors only.

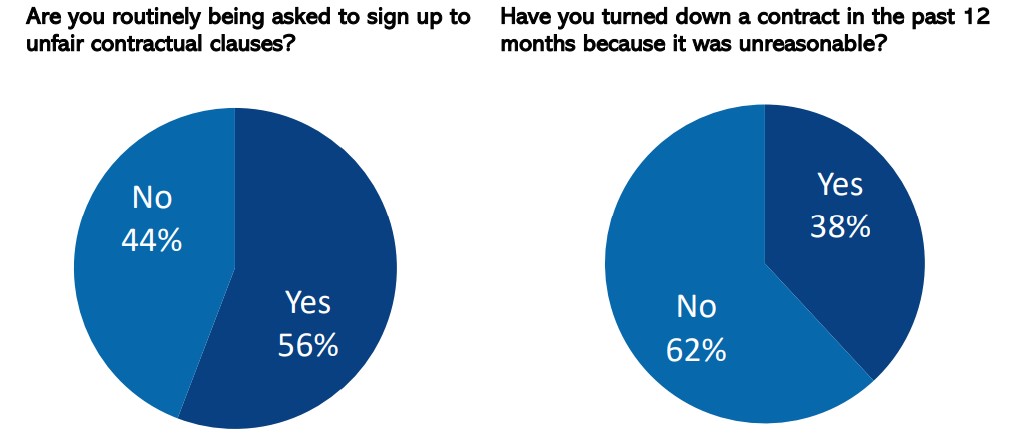
The survey also explored some of the concerns that are currently being experienced related to risk dumping through the supply chain.

Commenting on the data FIS CEO Iain McIlwee stated:

“The numbers clearly shows that the supply chain continues to be hit by inflationary pressures.  Some of the contractual issues are also a worry, close to 60% of our specialist members are being asked to sign unfair contracts.  Encouragingly there is evidence here that the Responsible No is being exercised, but the numbers are still out of balance.  There is also evidence that design, programme and compliance risk are increased with over 70% stating that they routinely being asked to take more risk in terms of Design and close to 90% stating the same for programme.  These numbers are not surprising, but they are concerning, especially against the backdrop of rising cost and more limited insurance cover available“.

In 2024 FIS launched the Responsible No Campaign to help bring attention to the pressures that specialists are under and the indiscriminate risk dumping that is evident in parts of the supply chain.

IF you wish to participate in future wage rate surveys, please contact the FIS on info@thefis.org and we will make sure you recieve appropriate updates.