FIS State of Trade Survey Q1 2024: Inflation continues, contractual battles persist but hope on the horizon

FIS State of Trade Survey Q1 2024: Inflation continues, contractual battles persist but hope on the horizon

FIS Q1 2024 State of Trade Survey

FIS State of Trade Survey Q1 2024 highlights that inflation has slowed, but prices continue to rise due to raw materials and wages.  

Workloads reported by FIS members in the final quarter of 2023 were mixed.   Whilst a balance of 9% experienced growth, close to a quarter reported no changes quarter-on-quarter and the difference between those growing by over 5% and declining by over 5% was marginal.  

Looking to the next quarter (Q1 2024) the expectation for most is more positive with 30% anticipating growth of over 5%, but this is balanced by 34% expecting their market to level out and 23% expecting the market to tighten and a further. 

Members can dowload a full copy of the FIS State of Trade Survey Q1 2024 here

Alignment with wider industry forecasts

FIS data is gathered with the support of the COnstruction Products Association, who this week published the Construction Products Association’s Winter Forecasts..  Construction output is forecast to fall by 2.1% this year due to falls in private housing new build and repair, maintenance and improvement (rm&i) – the two largest construction sectors. The CPA forecasts that construction output will rise by 2.0% in 2025 in line with falling interest rates and a general economic recovery, which, in turn, could ease challenges in the housing and rm&i sectors. Recent disruptions in the Red Sea, however, have been identified as a key risk to the forecasts, potentially leading to supply issues such as delays and accelerating cost inflation.

Private housing – the largest construction sector – suffered a double-digit fall last year after a spike in mortgage rates hit housing market demand. Consequently, many house builders have reported a fall of around 25-35% in demand, in addition to the regulatory issues that smaller house builders continue to face in particular around planning, as well as water and nutrient neutrality. The lagged effect of higher mortgage rates is likely to continue to weigh upon property transactions this year with private housing output expected to fall by a further 4.0%. Looking to next year, a gradual fall in interest rates should boost demand with private housing output expected to rise by 4.0%. This doesn’t imply a speedy recovery however, as interest and mortgage rates are not expected to return to the record lows seen as recently as 2021 anytime soon. The lack of a government policy stimulus to help overcome high deposit and mortgage payment requirements, also means the recent peaks in housebuilding from 2022 are unlikely to be seen again until at least the end of the decade.

Private housing rm&i is the second-largest construction sector and activity continues to be on a general downward trend. The rising cost of living has hit discretionary household improvements spending. In addition, fewer property transactions last year led to a decline in refurbishment activity from new homeowners who typically make cosmetic improvements within the first 6-9 months of moving in. Smaller project work is likely to continue to remain flat in the first half of this year as household spending remains tight, whilst the continued fall in property transactions in the first half of this year is likely to hit larger project work for the remainder of 2024. This is likely to be partially offset though by strong activity on energy-efficiency retrofit such as insulation and solar photovoltaic work. Overall, private housing rm&i output is expected to fall by 4.0% in 2024 before growth of 3.0% in 2025.

In infrastructure, which is the third-largest construction sector, activity remains strong down on the ground. Work continues apace on HS2 Phase One despite the most recent cost increases, as well as on Hinkley Point C and the Thames Tideway Tunnel. Frameworks activity in the regulated sectors of roads, rail, water and electricity provides sustained levels of activity in the infrastructure sector too. Concerns remain, however, over pauses and delays to National Highways projects, as well as increasing uncertainty on the deliverability of plans in the water sector to deal with water quality issues through increased capital expenditure. Furthermore, at a local level, councils continue to face financial constraints and despite government announcing £8.3 billion of funding for potholes, resurfacing and roads projects to 2034, there is little evidence to suggest that this will lead to any uplift over the forecast period. As a result, overall, infrastructure output is expected to fall by 0.5% in 2024, a third successive marginal fall in output, before rising by 1.2% in 2025.

Commenting on the Winter Forecasts, CPA Economics Director, Noble Francis said: “The bad weather at the start of January has already affected the construction industry but there is still lots of time for a catch up in activity when the weather improves. The bigger problems for the industry are the hits to activity last year in its two largest sectors – private housing and private housing rm&i. These are likely to continue into 2024. Even with expected falls in interest and mortgage rates in the second half of this year, rates are likely to remain relatively high and so demand in the housing market, house building sector and rm&i sector is likely to remain subdued overall.

“Given the importance of housing to the UK economy, it was disappointing that the Chancellor’s Autumn Statement last year had little to help the beleaguered sector. It is critical that we see measures to help boost house building and homeownership from government in the upcoming Spring Budget. Furthermore, government should do more on infrastructure delivery given that the sector is set for its third consecutive fall in output. This is despite announcements from government on new projects to compensate for the cancelling of the Northern leg of HS2.”
An Overview of the Modification to Payment Practices and Performance Regulations of 2024

An Overview of the Modification to Payment Practices and Performance Regulations of 2024

The CLC has released a statement on Reporting on Payment Practices and Performance (Amendment) Regulations 2024

On Wednesday 10 January the Department for Business and Trade (DBT) laid the Reporting on Payment Practices and Performance (Amendment) Regulations 2024.

These Regulations amend existing regulations, which impose a requirement on large companies and limited liability partnerships (LLPs) to publish certain information twice per financial year about their practices, policies and performance in relation to paying suppliers. These Regulations extend the Principal Regulations and the LLP Regulations beyond their current sunset date of 6 April 2024 to 6 April 2031 and require additional information to be reported by qualifying companies and LLPs. This includes requirements for qualifying companies to publish information on the value of payments made within a qualifying period and information on payments that were not paid under qualifying contracts. The Regulations can be found here.

The Government response to the public consultation on the amendments to the Payment Practices and Performances Regulations 2017 was published alongside the Autumn Statement 2023, and confirmed the introduction of a requirement for qualifying businesses that are parties to construction contracts to report on their retention payment policy and key statistics in relation to retentions.

Legislation for the new retention reporting requirements is expected to be laid before Parliament in 2024. It is anticipated that qualifying business will commence data collation and include in their payment practices and performance reports during 2025.

FIS CEO Iain McIlwee added:

“It is great to see the changes that were announced in the Autumn are being carried into law, but a bit disappointing that we have to wait until 2025 before we start to see the benefit.  This is an area where FIS has long been calling for reform and has repeatedly highlighted the limitations with current reporting requirements that mask some serious underlying problems.  The new requirements will provide a more realistic measure of late payment of construction invoices and highlight problems related to retention and disputed invoices.This is a positive step, but better measurement is not in itself change.  As we head to the next General Election we will continue to lobby for reform of payment certification and retentions in construction and I am hopeful that the data that will start to come through will support our calls for change.  New Zealand recently legislated for retentions to be held in trust and the EU are bringing forward far tougher late payment regulations.  In the UK we are way behind on this and the supply chain is, as a consequence, getting even harder hit by the current levels of insolvency.”

Updates on the R&D Tax Credit Scheme for Construction Innovation

Updates on the R&D Tax Credit Scheme for Construction Innovation

The new R&D tax credit scheme, slated for launch in April 2024, has been closely followed by investors in construction innovation. The government has increased the tax credit from 1 April 2023 to 20% of qualifying expenditure, which is an excellent incentive to boost construction productivity. However, there were initial concerns that the text implied a restriction in claiming the tax credit in cases where the R&D stemmed from sub-contracting, which would have been disastrous for many SMEs and large businesses in the construction sector.

Following close engagement with the government, the Construction Leadership Council (CLC) is pleased to report that specific positive references to subcontracting and the construction industry have been included in the Autumn Statement, with the aim of preserving current eligibility for the tax credit. The CLC, however, had valid concerns regarding the draft wording of the legislation released in the Draft Finance Bill 2023-24, which could still pose problems for the construction industry, where R&D activities had been “contemplated” further up the chain. The CLC is committed to ensuring that the R&D tax credit remains available to all firms in the construction supply chain that initiate their own R&D activities. HMT and HMRC have confirmed their willingness to work with the CLC and other industry professionals to ensure that the guidance is clear and that the final legislation reflects the position in the Autumn Statement. Real-world examples and case studies, including those from the construction industry, will be included in the guidance note, which should be available by early 2025.

Miranda Chamberlain, Group Head of Tax at Mace Group, shared these important updates.

Latest FIS Wage Rate Survey

Latest FIS Wage Rate Survey

To help monitor wage rate inflation (and other contractual issues), FIS launched in 2021 The FIS Wage Rate Index. The aim of this work is to support contract negotiations and to help track the impact of labour shortage on the cost breakdown of projects.

The survey is conducted every six months and FIS is asking all contractor members to take part. Data is published as a price index to allow for regional rate variations and all company specific data is managed in the strictest of confidence. The survey covers core trade roles, labourers, apprentices and construction and site managers.

THE DETAILED RESULTS OF THE SURVEY WILL BE MADE AVAILABLE EXCLUSIVELY TO CONTRIBUTORS.

You can complete the survey via the link here. The survey will close early in the New Year. If you cannot complete, please share the link with the person in your business who can.

Your support is, as ever, appreciated.

Construction Sector Facing Weakness Across the Supply Chain

Construction Sector Facing Weakness Across the Supply Chain

According to surveys conducted throughout the construction supply chain, the sector experienced a decline in activity during Q3 of 2023. Heavy side and light side manufacturers experienced sales declines, while chartered surveyors saw their workloads decrease. Small and medium-sized contractors, as well as civil engineering contractors, also saw their net workload balances weaken. The surveys revealed that forward-looking questions all pointed to a deteriorating backdrop for the next year. Concerns over demand strength, tighter financial constraints due to raised interest rates, and a decrease in new enquiries – including in sectors that had previously driven construction activity – were all noted. Additionally, construction costs continued to rise, outpacing increases in tender prices and reducing profit margins.

The CPA’s Construction Trade Survey brings together results from surveys of building contractors, specialist contractors, civil contractors and product manufacturers. It provides a pan-industry assessment of current and expected conditions.

Members can access the Trade Survey here

Rate of inflation reducing, but costs are still going up warns FIS

Rate of inflation reducing, but costs are still going up warns FIS

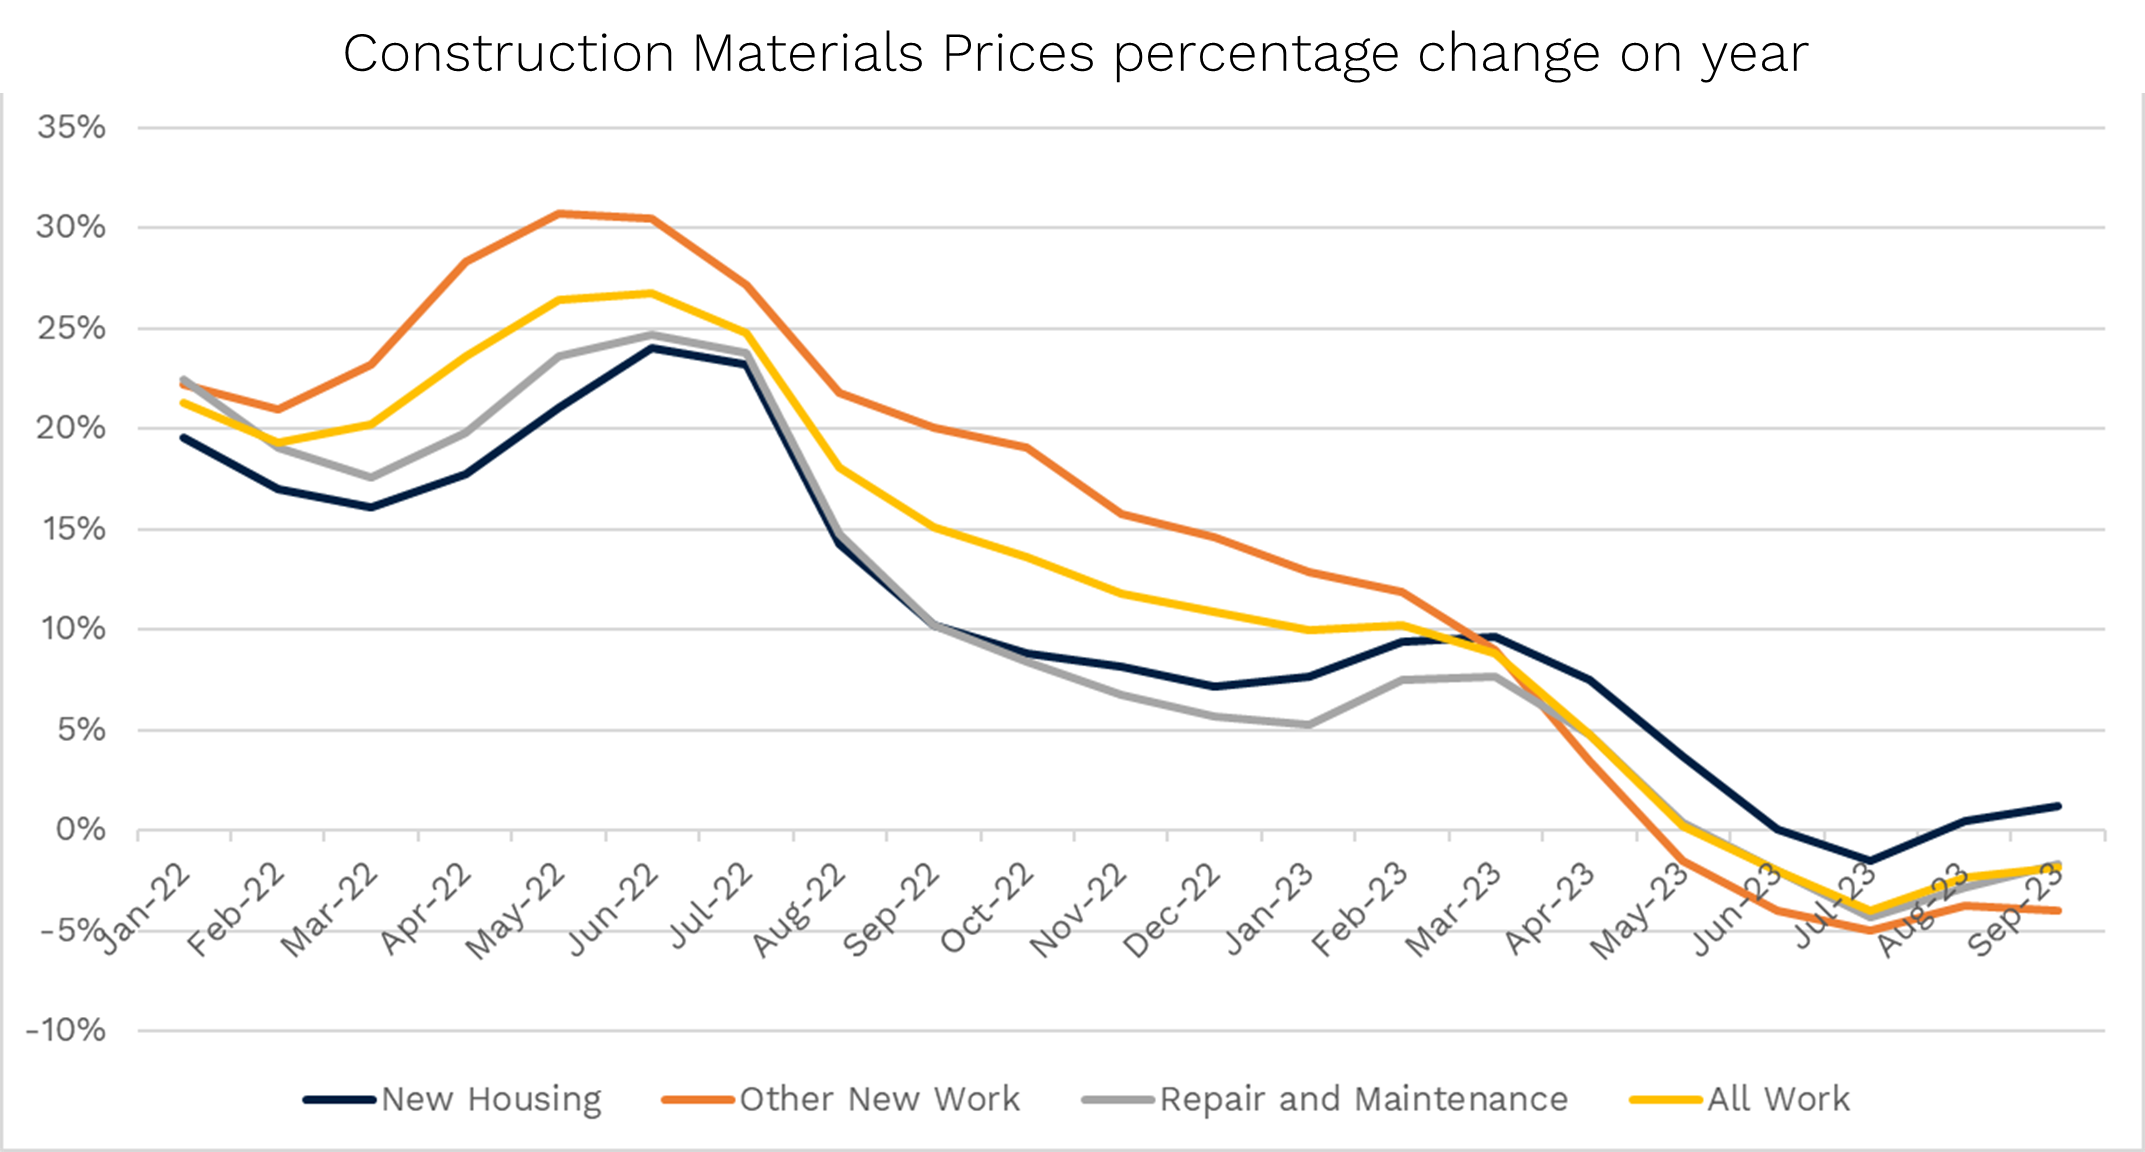
The Building Cost Information Service (BCIS) has reported at the start of November that construction materials prices for all work fell by 1.8% in the 12 months to September 2023, according to new figures from the Department for Business and Trade. This was a smaller decrease than the 2.3% drop seen in the year to August 2023.  However this does not mean inflation is over and costs are falling, warns FIS.
 
Commenting on the data FIS CEO, Iain McIlwee stated:

“Whilst it is encouraging to see the rate of inflation coming down, this index does not necessarily reflect what individual contractors are experiencing on the ground.  Whilst generic data is helpful, the index is broad and there are fairly large differences between the different material types and the headline may not align to the specific products specialists are procuring or deals they may be locked into.

“Beyond this it is important to remember that materials only typically reflect around 30-40% of the cost of construction and we have continued to see wage rate inflation trending high – the FIS Wage Rate and Productivity Survey published this week pointed to continued day rate inflation across all the key trades in our sector.

“The final cost to factor in, is that new regulation is putting pressure on all in the supply chain and the cost of compliance is impacting prelims.

“Looking ahead, the signs seem to be that the period of hyperinflation has passed, but this doesn’t mean real world prices are falling and we cannot be complacent.  The full impact of recent events in the Middle East on energy and material prices remains unknown and just because work may be slowing down in some areas it does not necessarily follow that prices will drop.”


Source: Department for Business & Trade – Monthly Bulletin of Building Materials and Components, Table 1

If you are interested in participating in the FIS Wage Rate Survey and receiving a copy of the data, email iainmcilwee@thefis.org (data goes back to 2020, but is only available to contributing companies).